RETIREMENT & LEGACY · INSIGHTS
Save my seat
FOR SINGAPOREANS AGED 45 AND OVER · LIVE ONLINE
TRAINING STARTS IN
Free 60-Minute
Retirement Training
Will Show You How The
Wealthy Optimise Their
CPF & Investments
While Reducing Their
Risk!
Learn how to make the most of your CPF and investments,
how different income sources may work together, and the key
CPF decisions waiting at 55 and 65.
Make the most of your CPF and investments in a retirement income plan.
Different income sources and how they may work together for retirement.
A simple 3-step framework for planning your retirement income.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
*Illustrative only. Any figure depends on your capital, time horizon and risk profile, and is not a forecast or guarantee.
FREE TO ATTEND
Save your seat
[VALIDATE: Date] · [VALIDATE: Time] SGT · Live online
Free to attend. The replay is sent to every registrant.
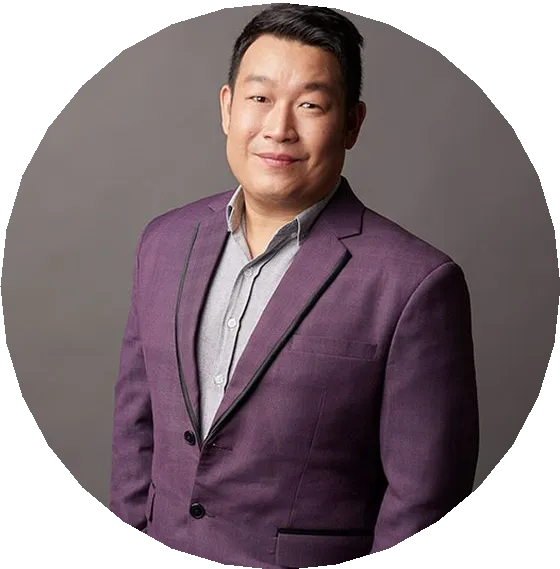
Presented by Fergus Tan
Senior Partner
WHY THIS MATTERS
When your salary stops, where will
your retirement income come from?
Most plans focus on what you own. Fewer look closely at how it could
support the retirement lifestyle you want, and for how long.
Retirement income planning is about more than how much you save.
It is about how your CPF, savings and investments may work together
to support the lifestyle you want.
TWO DECISIONS WORTH UNDERSTANDING EARLY
55 & 65
The two ages when key CPF decisions come up for most
Singaporeans.
Understanding your options before these decisions arrive is
one of the most useful things you can do at this stage.
WHAT YOU WILL WALK AWAY WITH
Your CPF and investments, as part
of a retirement income plan
Retirement income planning is about more than saving. Here is what you
will leave understanding.
01
What your retirement income could look like
How illustrative modelling may be
used to think through different
income sources, time horizons and
planning assumptions.
will leave understanding.
02
6 common retirement planning gaps
Idle cash, the wrong risk level, CPF
on autopilot, overlapping
insurance, and no income plan.
Common gaps worth checking for.
03
Match your plan to your risk tolerance
Conservative, balanced or growth.
How your risk tolerance may shape
the mix of CPF, savings and
investments in your plan.
04
Put idle cash to work
Key considerations when using
savings, CPF and investments as
part of a retirement income
strategy.
05
Make the most of your
CPF
How CPF top-ups and CPF LIFE
options may fit into your retirement
income plan.
06
The Hybrid Income Framework
The simple 3-step approach Fergus
teaches: See it, Match it, Build it.
Everything on one page, matched
to your risk, built into a plan.
WHO THIS IS FOR
This masterclass is built for you if
1
You are 45 or older and retirement is close enough to feel real
2
You have savings, CPF or investments but no clear plan to turn them into income
3
You want a clear retirement income plan, not just a pile of savings
4
You want your savings and investments working towards your retirement goals
5
You want your CPF and investments working together, not in separate silos
6
You would rather
understand your options
than decide under time
pressure later
THIS IS NOT FOR YOU IF
You are looking for hot stock tips or a way to get rich quickly.
You want someone to take unnecessary risks that keep you up at night.
You are not willing to look honestly at where your retirement plan stands today.
A COMMON ASSUMPTION
Most people think retirement is a
saving problem
It is also an income question. Here is a fuller way to look at it.
A COMMON ASSUMPTION
A FULLER PICTURE
Saving more is the whole answer.
How savings are structured may
matter as much as how much you
save.
CPF LIFE will cover everything.
CPF LIFE may form one part of your
retirement income, alongside your
savings and investments, depending on
your circumstances.
Cash always feels like the safe option.
Over time, inflation may reduce
what your cash can buy.
It is all about how much I have saved.
How your resources may support you
over a long retirement also matters.
| A Common Assumption | A Fuller Picture |
|---|---|
| Saving more is the whole answer. | How savings are structured may matter as much as how much you save. |
| CPF LIFE will cover everything. | CPF LIFE may form one part of your retirement income, alongside your savings and investments, depending on your circumstances. |
| Cash always feels like the safe option. | Over time, inflation may reduce what your cash can buy. |
| It is all about how much I have saved. | How your resources may support you over a long retirement also matters. |
WHAT SHAPES YOUR RETIREMENT INCOME
There is no single right number,
only considerations.
Rather than a fixed figure, a retirement income plan weighs several factors.
Here are some of the main ones.
RISK TOLERANCE
How much market movement you can be comfortable with.
TIME HORIZON
How many years your plan may need to support you.
INFLATION AND NEEDS
How rising costs and your income needs may change over time.
Other considerations include liquidity needs, market volatility,
diversification, your CPF and other retirement resources, and the
need for periodic review. For educational purposes only. Outcomes
depend on individual circumstances and market conditions.
THE FRAMEWORK YOU WILL WALK AWAY WITH
A simple framework: See it, Match
it, Build it
01
See it
Lay out everything you own on one page. Cash, CPF, SRS, insurance, investments, property. You cannot plan what you cannot see, and most people have never seen it all together.
02
Match it
Find the risk level you can actually live with. How much up and down can you handle, and still sleep at night? Get it right and the plan almost builds itself.
03
Build it
Bring the parts together into a retirement income strategy suited to your circumstances, across spending, growth and income.
YOUR PRESENTER
The person teaching this
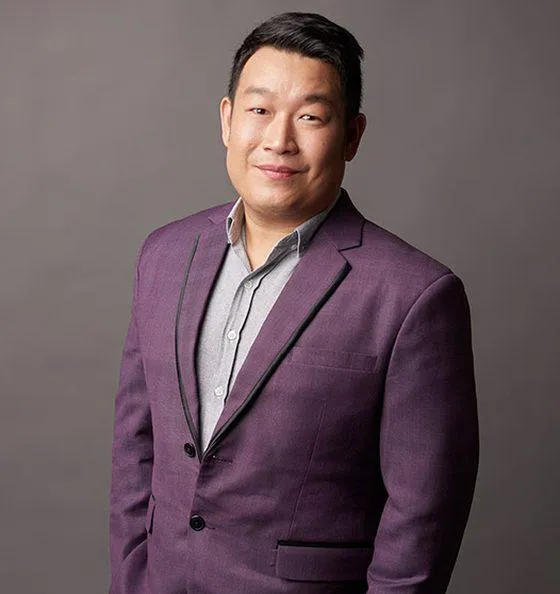
“I have sat with hundreds of households. The ones who planned early, and the ones who wished they had. My aim today is to help you understand your options and plan with more clarity.”
Fergus Tan
Senior Partner · Deputy Vice President (Reg. No. TCF100060651)
The Hybrid Income Framework, a simple 3-step approach to retirement income planning: See it, Match it, Build it.
Focused on income and risk, not product pitches. The plan starts with what you can live with.
Works with pre-retirees and retirees across Singapore, in plain English, one to one.
WHY NOW, NOT LATER
The best time to plan your
retirement income is before
you need it
Planning earlier gives you more time to review your options,
so you can aim to retire on your own terms, rather than having
to downgrade your lifestyle later.
SAVE YOUR SEAT
One hour on the key considerations in retirement income planning
Free to attend. The replay is sent to every registrant.
How your CPF, savings and investments may work together
How to match a plan to a risk level you can live with
A simple 3-step framework for planning your retirement income
FREE TO ATTEND
Save your seat
[VALIDATE: Date] · [VALIDATE: Time] SGT · Live online
Free to attend. The replay is sent to every registrant.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
BEFORE YOU REGISTER
Questions people ask right before
they sign up
Is this a sales session?
Who should attend?
I already have a financial adviser. Is this still relevant?
I have been burned before and I worry about risk.
What if I cannot attend live?
Is my information safe?
Ready to plan your
retirement income with
more clarity?
Register for the free masterclass and learn how your CPF, savings and investments may work together in a retirement income plan. Free to attend, with the replay sent to every registrant.
[VALIDATE: Date], [VALIDATE: Time] SGT
RETIREMENT & LEGACY · INSIGHTS
Important. This masterclass is for general educational purposes only and is intended to help Singaporeans understand retirement income planning concepts. It is not financial, legal, tax, or investment advice, and it does not constitute a recommendation or an o!er to arrange or sell any financial product. Any figures, examples or illustrations shown are for explanation only and are not guarantees of future results. Registration does not create an adviser-client relationship. Any planning decisions should be made with a licensed adviser who has reviewed your own circumstances.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
Presenter disclosure:
Fergus Tan is a Deputy Vice President representing Manulife Financial Advisers. Rep No: TCF100060651 This event is organised for educational purposes and is not a!iliated with or endorsed by the Monetary Authority of Singapore.
By submitting your information, you agree that Retirement and Legacy Insights may collect, use and disclose your personal data as provided in this form, in accordance with the Personal Data Protection Act 2012 and our data protection policy. You may withdraw consent at any time.
This site is not part of the Facebook website or Facebook Inc. It is not endorsed by Facebook in any way. FACEBOOK is a trademark of FACEBOOK, Inc.
© 2026 Retirement and Legacy Insights. All rights reserved.